
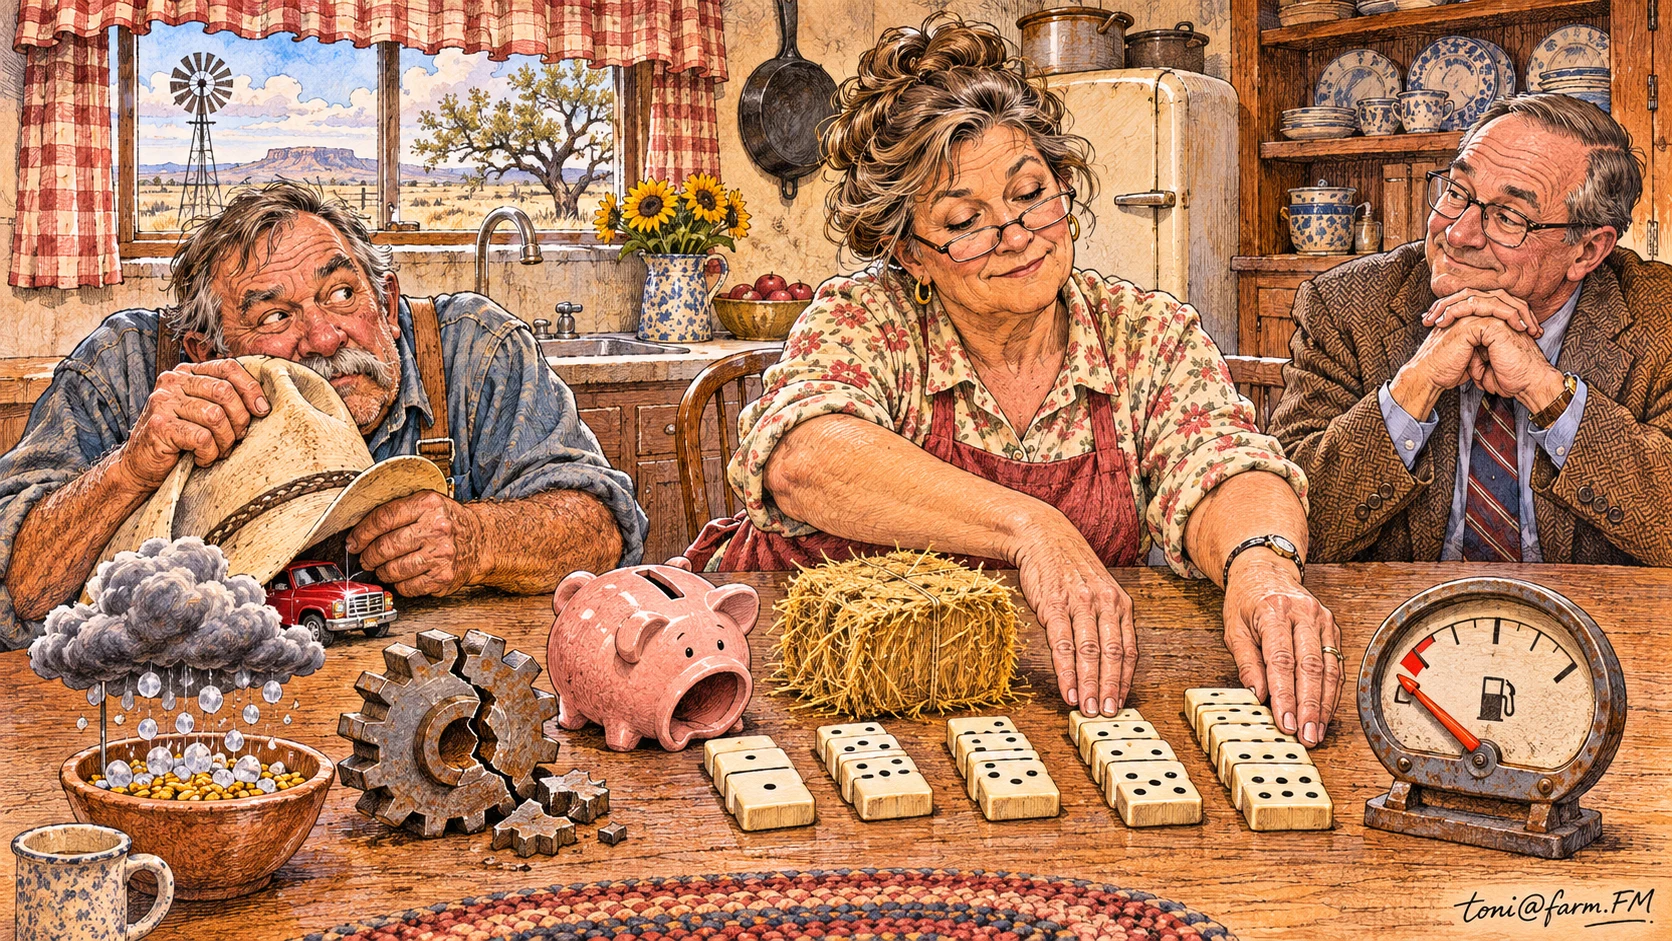
LEVELLAND, Texas — Farm risk management has identified farming as the largest remaining threat to a West Texas farm, followed closely by weather, markets, machinery and Clyde Mercer’s belief that the fuel gauge becomes pessimistic near empty.
Clyde “Straight Row” Mercer conducted his first formal risk review after his lender asked for a business-continuity plan. Clyde submitted a note reading, “Continue business.”
The lender returned it with three pages of questions.
“This is government-level paperwork,” Clyde said.
His wife, Marlene, observed that the bank was privately owned and merely curious how it would be repaid.
Farm Risk Management Opens a Family Meeting
Marlene used the RiskManagementHub to organize price risk, production risk, weather, insurance, liquidity, safety, biosecurity and business continuity. The site included worksheets and a financial stress test designed to model seasons nobody ordered.
Clyde listed his risks on the kitchen table.
For weather, he wrote “yes.”
For prices, he wrote “apparently.”
For machinery, he pointed toward the shop and said the evidence was self-documenting.
Marlene separated hazards by likelihood, financial consequence, warning time and possible response. Clyde wanted a fifth category called “things probably invented by the banker.” It contained interest, documentation and the requirement that arithmetic continue all the way to the bottom of the page.
The Stress Test Hurts the Budget’s Feelings
They began with a baseline cash-flow projection. Then they reduced yield, lowered commodity prices, raised feed and fuel costs and delayed one customer payment.
The spreadsheet turned red with the speed of a sunburned auctioneer.
Clyde accused the calculator of lacking confidence in agriculture.
Marlene explained that a stress test is not a prediction. It shows which combination of trouble creates a cash shortage and how early the family must respond. Waiting until the checking account makes a noise is not an early-warning system.
They set triggers. If rainfall and forage conditions deteriorated, they would price hay early and review herd numbers. If projected cash dropped below their reserve target, they would delay optional equipment, update the lender and review marketing alternatives.
Clyde asked whether a new pickup counted as optional equipment.
Marlene entered it under “uncontrolled optimism.”

Insurance Discovers the Shed Has a Name
Next they reviewed policies, deductibles, covered property, exclusions and claim contacts. Clyde had insured the main equipment but described several smaller structures as “that shed,” “the other shed” and “the shed the wind moved.”
Marlene photographed assets, recorded serial numbers and stored copies away from the farm. Clyde argued that he could identify every implement by the sound it made while failing.
The USDA Risk Management Agency provides official information about federal crop insurance and agricultural risk programs. Policies, deadlines and coverage details require actual documents and qualified agents, not a neighbor who remembers hearing something at the sale barn.
Clyde called his insurance agent and asked whether hail was covered.
“Under the applicable policy terms,” the agent said.
“What about emotionally?”
“No.”
They added renewal dates and reporting deadlines to the calendar. The calendar now contained more agricultural strategy than Clyde’s first continuity plan.
The Backup Plan Needs a Person Who Knows the Password
Business continuity raised a harder question: what happens if Clyde cannot work for a week?
Clyde said Marlene would run the farm.
Marlene said she already ran the farm; the question concerned Clyde’s jobs.
They documented livestock routines, field locations, equipment instructions, key contacts, account procedures and emergency shutoffs. They named alternates for feeding, irrigation and payroll. The dog was removed from payroll after failing the signature requirement.
Clyde kept critical information in his head, a storage system with no export function and frequent password resets. Marlene created a secure record and tested whether another responsible adult could find what was needed.
That adult found the fuel account, veterinary contact and irrigation controls. Nobody found the socket set.
A Risk Register Does Not Stop Weather
By evening, the Mercers had a short risk register, response triggers, insurance records, emergency contacts and a ninety-day cash-flow contingency. Nothing prevented drought, hail, price declines or a bearing from disintegrating at 5:02 p.m. Friday.
The plan did make the first response less expensive and the second phone call less surprised.
Clyde admitted the meeting had value. He even added one final risk: “Failure to listen to Marlene.”
He rated it likely, severe and already occurring.
Marlene assigned the mitigation.
Farm.FM Disclaimer
This report is entirely a human collaboration between two sentient beings — the world’s oldest tenured professor and a philosophy major turned dairy farmer. Neither offers insurance, legal or financial advice, and both recommend testing a continuity plan before the only person who knows the password drives to town with the password in his head.
Last Updated on November 17, 2026 by Alan Nafzger
A risk-management plan that concludes farming is the risk has finished its homework, and farm risk and financing guides are for the part you can actually insure.